A $35,000 kitchen remodel can add daily comfort and meaningful resale appeal. Financing it with the wrong loan, however, can leave you paying more than the project deserves. The best loans for home renovations depend on how much you need, how quickly you need it, your available home equity, and whether you want a predictable payment or flexible access to funds.
The right answer is not always the loan with the lowest advertised rate. A short project may call for a smaller unsecured loan. A major addition may justify tapping equity at a lower rate. Before choosing, match the financing to the work itself - and to the way you plan to repay it.
Best Loans for Home Renovations: Your Main Options
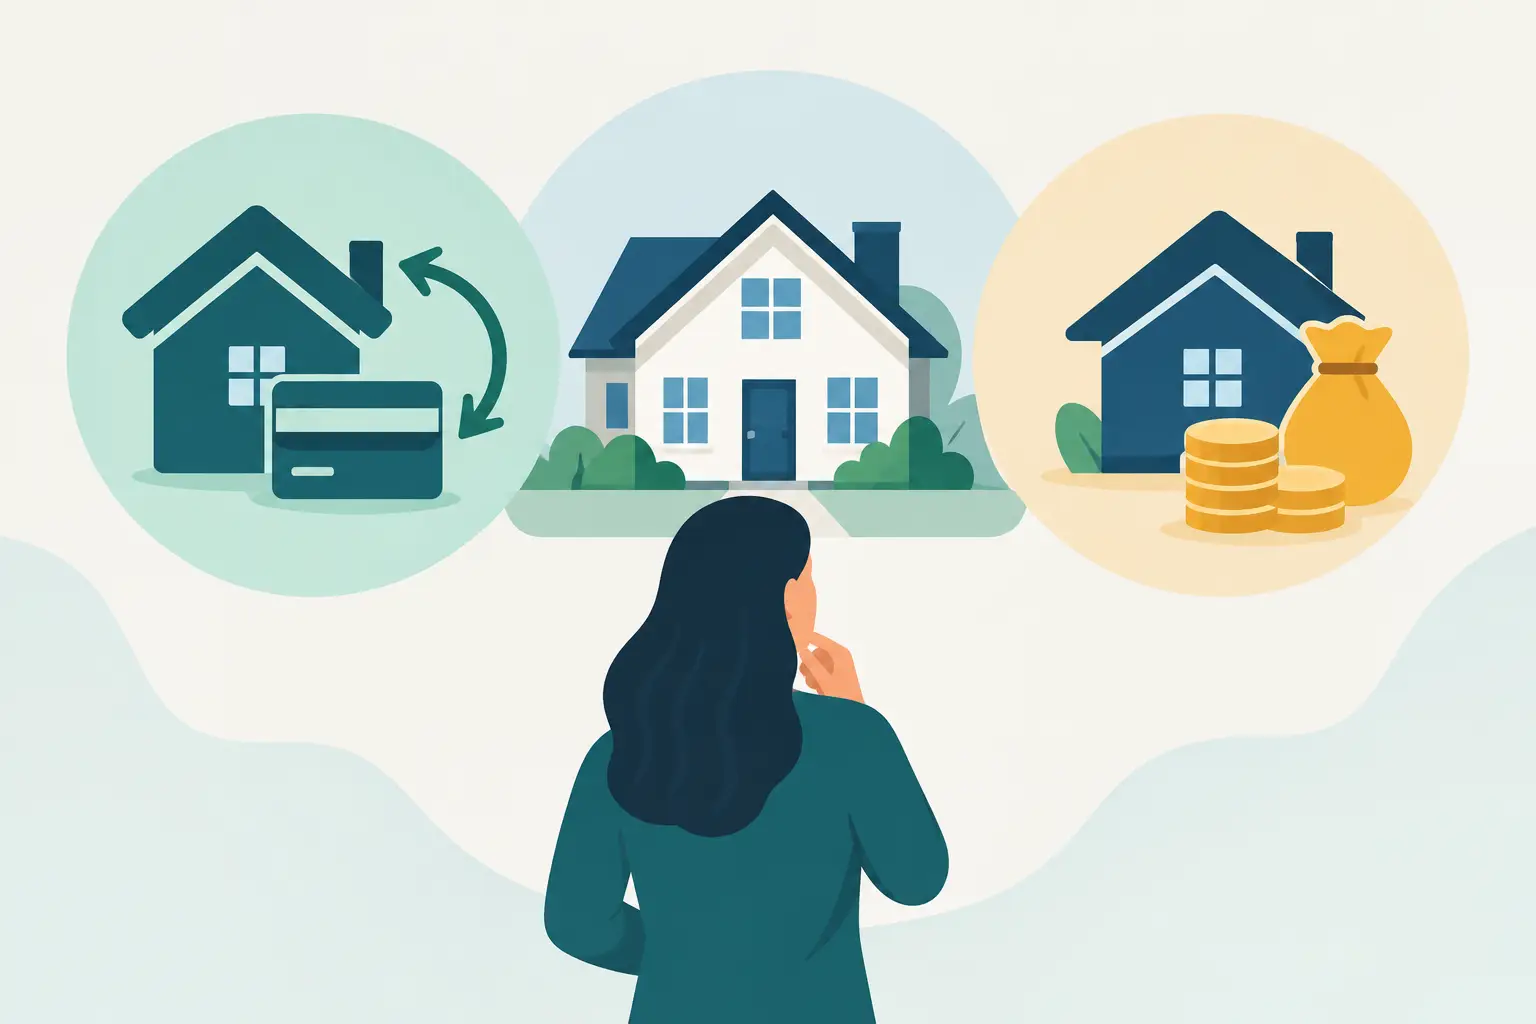
Homeowners generally finance renovations with a home equity line of credit, a home equity loan, a cash-out refinance, or a personal loan. Each option solves a different problem.
HELOC: Flexible funding for projects completed in stages
A home equity line of credit, or HELOC, lets you borrow against available equity up to an approved limit. Rather than receiving one large lump sum, you can draw funds as contractor invoices arrive. That can make a HELOC especially useful for phased renovations, such as a kitchen remodel followed by flooring, landscaping, or a bathroom update.
During the draw period, many HELOCs allow interest-only payments. This can keep initial payments lower, but it also means the balance may remain largely unchanged until the repayment period begins. HELOCs commonly have variable interest rates, so your payment can rise if market rates move higher.
A HELOC can be a strong fit when you have substantial equity, a solid credit profile, and uncertainty around the final project cost. It is less ideal if you need a fixed payment from day one or if you would be tempted to keep drawing on the line after the renovation is complete.
Home equity loan: One amount, one fixed payment
A home equity loan is often called a second mortgage because it sits alongside your existing mortgage. You receive a lump sum and repay it in regular installments, usually with a fixed interest rate. For homeowners who know the exact cost of a new roof, HVAC replacement, or planned remodel, that certainty can be valuable.
The trade-off is flexibility. If your contractor bid is $60,000 and the work comes in under budget, you have still borrowed the full amount. If unexpected structural repairs push the project over budget, you may need another funding source. Still, for a defined project and a household that wants stable monthly payments, a fixed-rate home equity loan can be a clear, disciplined choice.
Cash-out refinance: Replace your mortgage and fund the renovation
A cash-out refinance replaces your current mortgage with a new, larger loan. The difference between the new loan amount and what you owe, minus closing costs, is paid to you in cash. It can provide substantial funding for major improvements such as an addition, whole-home renovation, or extensive repairs after purchasing an older property.
Because the new loan replaces your first mortgage, cash-out refinancing deserves careful comparison. It can make sense when you can improve your mortgage terms, need a larger amount of money, or want one monthly payment instead of two. But if your current first-mortgage rate is significantly lower than today’s available rates, refinancing the entire balance could increase your long-term borrowing cost.
This is where the total loan picture matters more than a single rate. Compare the new payment, closing costs, term length, cash received, and interest you could pay over time. Extending a loan term can lower the monthly payment while increasing total interest. That may be worthwhile for your budget, but it should be a deliberate decision.
Personal loan: Fast financing without using home equity
A personal loan does not use your home as collateral. Approval is generally based on credit, income, debts, and other underwriting factors. Funding can be faster than mortgage-based options, and there are no property valuation requirements in many cases.
The convenience comes at a cost. Personal loans often carry higher interest rates and shorter repayment terms than loans secured by home equity. They can work well for smaller, urgent projects, such as replacing appliances, repairing plumbing damage, or covering a modest bathroom refresh. For a six-figure renovation, the payment may be too high to be practical.
How to Choose a Renovation Loan That Protects Your Budget
Start with a realistic all-in project figure. Your contractor’s initial estimate is only one part of the budget. Include permits, design work, materials, temporary living arrangements if needed, and a contingency reserve for surprises behind walls or under floors. A contingency of 10% to 20% is common for substantial renovations, especially in older homes.
Next, consider whether your costs will arrive all at once. A home equity loan or cash-out refinance may be sensible if you need a large lump sum immediately. If the project will unfold over months and invoices will vary, a HELOC may prevent you from paying interest on money you have not yet used.
Then review your existing mortgage. Homeowners with a favorable first-mortgage rate should take extra care before choosing cash-out refinancing. A second-lien option, such as a HELOC or home equity loan, may allow you to preserve that low rate while borrowing only what the renovation requires. On the other hand, homeowners with a higher current rate may find that a cash-out refinance creates a cleaner overall financial structure.
Your repayment horizon also matters. If you expect to sell within a few years, closing costs and long-term interest may outweigh the value of a new loan. If you plan to remain in the home for a decade or more, improvements that increase usability and market appeal may justify more deliberate financing.
Approval Factors Lenders Will Review
Equity is central to mortgage-based renovation financing. Lenders typically look at your loan-to-value ratio, which compares your mortgage balance and proposed borrowing to the home’s appraised value. More equity generally creates more options, though eligibility varies by loan program and borrower profile.
Lenders will also evaluate your credit history, debt-to-income ratio, income, assets, and property type. Strong credit can improve pricing, but it is not the only factor. Self-employed borrowers, commission earners, and other nontraditional income households may need a lender that can evaluate their complete financial picture rather than relying on a one-size-fits-all approach.
Do not assume a past decline means renovation financing is out of reach. The structure of the loan, the amount requested, the property value, and the documentation available can all change the outcome.
Avoid These Costly Renovation Financing Mistakes
Do not finance based solely on what a lender says you may qualify for. Borrowing to the maximum can turn a home upgrade into a payment burden, particularly when property taxes, insurance, or contractor costs rise. Build your payment around a comfortable monthly budget, not an approval ceiling.
Avoid treating variable-rate financing as fixed-rate financing. If you choose a HELOC, ask how the rate is set, how often it can adjust, whether there is a rate cap, and what the payment could look like if rates increase. A low introductory payment is helpful only if you can manage the payment that follows.
Finally, be cautious with contractors who pressure you to use a particular financing arrangement before you have reviewed the terms. Choose your contractor based on licensing, insurance, references, scope, and contract clarity. Choose your loan based on cost, fit, and your ability to repay.
Get Financing Built Around Your Next Move
A renovation loan should help you improve your home without weakening your financial position. US Mortgages can help homeowners compare equity-based options, evaluate refinance scenarios, and find financing that fits the project rather than forcing the project to fit the loan.
Bring your estimated budget, current mortgage details, and timeline to the conversation. With the right structure in place, you can move forward with a renovation plan that adds value to your home and confidence to your next payment.